If you’re planning to build a custom home on the Space Coast, one of the first questions you’ll consider is how to pay for it. Custom home building doesn’t work like buying an existing house, so the financing looks different too. The most common path our clients take is a construction-to-permanent loan, sometimes called a construction-perm loan. It’s worth understanding how this works before you sit down with a lender, so you walk into the process with confidence instead of surprises.
What Is a Construction-Perm Loan?
A construction-perm loan combines two loans into one. During the building phase, the bank releases funds in stages as the home progresses. Once construction is complete, the loan automatically converts into a standard mortgage, so you’re not applying twice or closing twice. Regardless of where you’re building, whether the project is in Melbourne, Satellite Beach, or Titusville, this is usually the simplest way to finance a custom build. The process is designed to align with construction costs.
The other path we see regularly is a cash contract, where the buyer funds construction directly rather than going through a bank. Both routes work well with a custom home builder like DiPrima, and which one makes sense really just depends on your personal finances and goals.
Shop Around for Your Lender
One thing we tell every client: you’re free to work with any reputable lender who approves you. We don’t require you to use one specific bank. Local institutions like Space Coast Credit Union and Community Credit Union are popular choices among our clients, but they’re far from the only options. Rates, terms, and draw processes can vary quite a bit from one lender to another, so it pays to shop around and compare a few before committing. A little research upfront can save you real money over the life of the loan.
How the Draw Schedule Works
Whether you’re financing through a construction-perm loan or paying with cash, the payment structure is the same. We use a five-draw schedule, meaning funds are released at five milestones throughout the build:
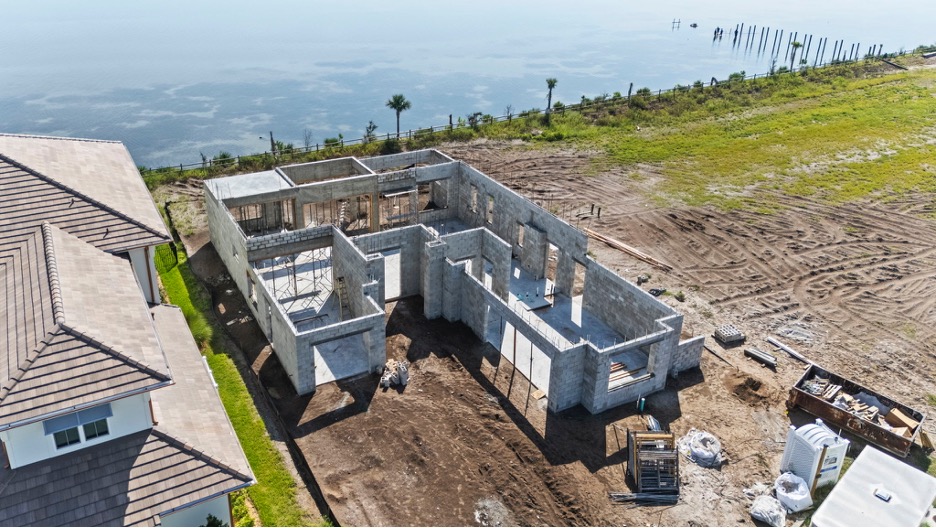
- Completion of the block
- Roof dry-in
- Completion of drywall
- Installation of cabinetry
- Completion of the house
For construction-perm loans, these draws come from the bank as each milestone is verified. For cash contracts, the buyer provides the funds directly at the same points. Either way, the structure keeps everyone on the same page: you know exactly what triggers each payment, and we know the project is funded as it moves forward.
In both scenarios, we typically ask for a $25,000 deposit at the signing of the contract. This deposit gets the ball rolling on preconstruction work like planning, permitting, and scheduling before the first draw is ever collected.
Why This Matters for Your Build
Understanding your financing options early makes the entire custom home building process smoother. When you know how the draws work and what your lender expects, you can plan your budget with fewer surprises along the way. It also helps you have better conversations with your builder, since you’ll understand how the construction schedule and the payment schedule move together.
Whether you’re dreaming of a home in Melbourne near the Eau Gallie Arts District, a coastal build in Indialantic close to the water, or a spacious property out in Grant, the financing process looks largely the same. What changes is the home itself, and that’s where working with an experienced builder makes the difference.
Ready to Talk Financing?
If you’re considering a custom home on the Space Coast, we’re happy to walk you through what financing looks like for your specific situation, whether that’s a construction-perm loan through your bank of choice or a straightforward cash contract. Reach out to DiPrima Homes to start the conversation.